How Car Modifications Affect Auto Insurance Rates and What You Can Do
- By the dedicated team of editors and writers at Newsletter Station.
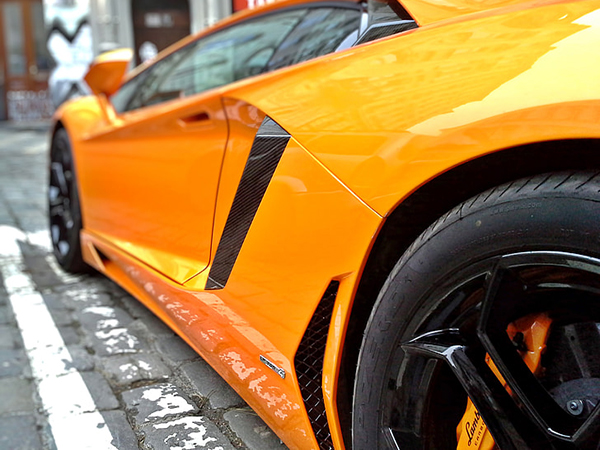
The allure of car modifications is undeniable for enthusiasts and everyday drivers alike. From engine upgrades that boost performance to sleek body kits and personalized interior touches, modifications allow drivers to tailor vehicles to their tastes. However, amid the excitement of customizing a ride, many overlook an essential factor: the impact of car modifications on auto insurance rates.
Modifications can significantly influence insurance premiums, so understanding this relationship is critical for anyone contemplating or already investing in vehicle alterations. Here’s what car owners need to know:
Understanding the Basics
Insurance companies determine premiums based on risk, considering the likelihood and potential cost of claims. Car modifications are viewed as deviations from the manufacturer’s original design and can affect safety, performance, and overall insurability. Insurers evaluate these changes carefully, as alterations can increase the risk of accidents or costly repairs.
Factors Influencing Insurance Rates
Several key factors affect how modifications impact premiums:
Type of Modification
Performance upgrades, such as engine tuning, suspension enhancements, or turbocharging, often carry higher insurance premiums than cosmetic changes like paint jobs or aftermarket rims. Insurers assess modifications based on their perceived risk and potential impact on vehicle performance.
Value of Modifications
Expensive aftermarket parts or high-value customizations can increase claim costs, prompting insurers to adjust premiums accordingly.
Safety Implications
Modifications that compromise safety—such as non-certified aftermarket parts or alterations to airbags, brakes, or other critical systems—can elevate risk and lead to higher premiums.
Frequency of Claims
Insurance providers analyze historical data. If certain modifications correlate with higher claim frequency or severity, they can lead to higher premiums for vehicles with similar upgrades.
Tips for Managing Insurance Costs
While modifications may raise premiums, proactive strategies can help manage costs:
Disclose All Modifications
Complete transparency is crucial. Failing to report modifications can result in coverage gaps or policy cancellation. Provide detailed information on every upgrade to ensure accurate pricing and proper coverage.
Seek Specialized Coverage
Some insurers offer policies tailored for modified vehicles. These policies may cover aftermarket parts and modifications more comprehensively, giving peace of mind that your investment is protected.
Shop Around
Insurance rates vary widely among providers. Comparing quotes helps you find the best coverage at competitive prices while accounting for your vehicle's unique modifications.
Evaluate Overall Costs vs. Benefits
Consider whether the performance or aesthetic benefits of modifications outweigh the potential increase in insurance premiums. Making informed decisions helps balance enjoyment with financial responsibility.
Car modifications can personalize and enhance vehicles, but they can also affect insurance rates. By understanding how insurers assess risk, disclosing all changes, and seeking specialized coverage when needed, drivers can confidently enjoy their custom rides.
Whether you’re a seasoned gearhead or a casual enthusiast, navigating the intersection of car modifications and insurance requires careful planning. Staying informed and proactive ensures your vehicle reflects your personality while remaining adequately protected on the road.