- By the dedicated team of editors and writers at Newsletter Station.
Buying a home is one of the most significant financial decisions you'll make. The process involves many factors, including your income, savings, debt, down payment, and credit history. One of the most important pieces of the mortgage puzzle is your credit score.
Your credit score can influence whether you qualify for a mortgage, the interest rate you're offered, and the overall cost of borrowing. Understanding how credit works before you begin house hunting can help you make informed decisions and potentially put you in a stronger financial position.
Understanding Credit Scores
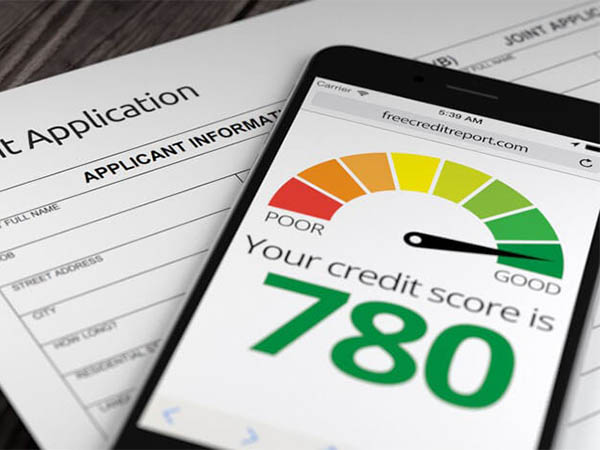
A credit score is a numerical representation of your credit history and how you've managed borrowed money. Most commonly used consumer credit scores range from 300 to 850, with higher scores generally indicating lower credit risk.
Mortgage lenders don't look at your credit score in isolation. They may also review your payment history, outstanding debts, income, assets, employment, and other financial information when evaluating your mortgage application.
You may also have multiple credit scores. Different scoring models and credit reporting agencies can produce different results, and the score you see through a consumer credit service may not be the same score a mortgage lender uses.
How Your Credit Score Affects Mortgage Rates
One of the most significant ways your credit can affect home buying is through your mortgage interest rate. In general, borrowers with stronger credit profiles may qualify for more favorable interest rates because lenders view them as lower risk.
Even a small difference in interest rate can substantially affect the total cost of a mortgage over many years. However, no single interest rate is tied to a particular credit score. Rates depend on factors such as the lender, loan type, loan amount, down payment, market conditions, and the borrower's overall financial profile.
For this reason, it's more useful to think of your credit score as one factor that can affect your mortgage pricing rather than assuming a specific score guarantees a particular rate.
Credit Score and Mortgage Eligibility
Your credit score can also affect whether you qualify for certain mortgage programs. Different mortgage types have different underwriting requirements, and lenders may set their own standards within program guidelines.
For example, FHA-insured loans can be available to borrowers with lower credit scores than some conventional mortgage options, although requirements vary based on the borrower's circumstances and down payment. VA loans, USDA loans, and conventional mortgages also have their own eligibility and underwriting requirements.
A lower credit score doesn't necessarily mean you can't buy a home. However, it may limit your options or lead to less favorable loan terms. A mortgage professional can help you understand which options may be available based on your complete financial picture.
Your Credit Score Is Not the Only Factor
While credit is important, lenders consider much more than your score when reviewing a mortgage application.
Your debt-to-income ratio, or DTI, is another important factor. This compares your monthly debt obligations with your gross monthly income and helps lenders evaluate whether you can comfortably manage additional debt.
Lenders may also consider your down payment, cash reserves, employment and income history, existing debts, and the type and amount of mortgage you're requesting.
A strong credit score can help, but it doesn't replace the importance of maintaining a healthy overall financial profile.
Steps to Improve Your Credit Before Buying a Home
If you're planning to buy a home and your credit isn't where you'd like it to be, give yourself time to strengthen your financial profile before applying for a mortgage.
Pay bills on time:
Payment history is an important component of credit scoring. Set up reminders or automatic payments where appropriate so you don't accidentally miss due dates.
Manage credit card balances:
The amount of revolving credit you're using compared with your available credit can affect your credit score. Paying down balances can help reduce your credit utilization.
Avoid unnecessary new credit:
Opening several new credit accounts or taking on additional debt shortly before applying for a mortgage can complicate your financial picture. Avoid applying for credit you don't need while preparing to buy.
Review your credit reports:
Check your credit reports for inaccurate or incomplete information. You can dispute information you believe is incorrect with the appropriate credit reporting agency.
Give yourself time:
Credit improvement generally doesn't happen overnight. If you're planning to buy a home, starting to review and improve your credit well before applying for a mortgage gives you more time to address potential problems.
Be Careful With Your Credit During the Mortgage Process
Once you've been preapproved or are actively shopping for a home, continue managing your credit carefully. Avoid taking on large new loans, making major purchases on credit, or opening multiple new accounts without first discussing the potential impact with your mortgage professional.
Remember that mortgage lenders may review your financial information again before closing. Keeping your finances stable throughout the process can help you avoid unexpected complications.
Start Preparing Before You Start House Hunting
Your credit score can play an important role in the home-buying process, affecting mortgage eligibility and potentially influencing the interest rate and loan terms you receive. However, it's only one part of a much larger financial picture.
If buying a home is one of your goals, check your credit early, review your reports, manage existing debt, and avoid unnecessary new credit. Taking these steps before you start shopping can give you a clearer picture of your financial position and help you approach the mortgage process with more confidence.