
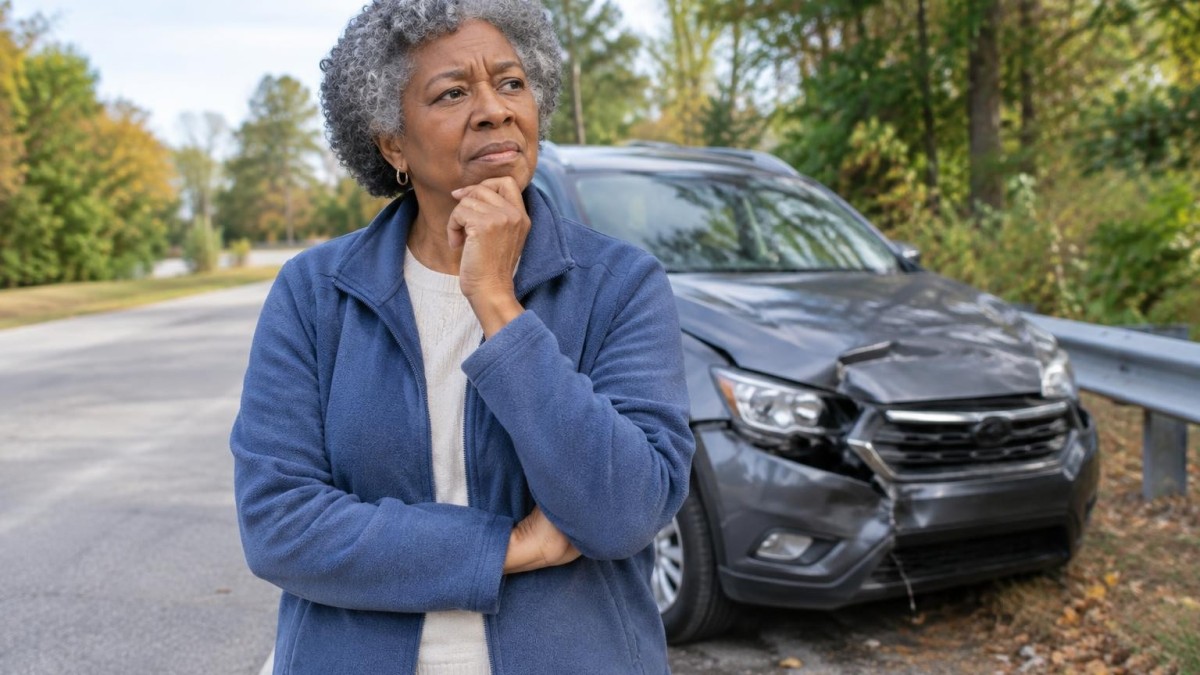
How a Single-Vehicle Accident Can Affect Your Insurance Costs
Even cautious drivers can find themselves in a single-vehicle collision—whether it’s hitting a tree, guardrail, or sliding off the road. These accidents may look minor but can lead to increased insurance premiums since insurers often treat them as "at-fault" incidents. Expect a possible rate hike at your next renewal or sooner, depending on your insurer and claim history.
Loss of Discounts and Impact on Claim-Free Benefits
Accident-free discounts reward careful driving, but a single-vehicle accident can temporarily eliminate these savings. Similarly, filing a claim might reduce or reset your no-claim bonus, which normally lowers your insurance costs over time. Some insurers offer accident forgiveness programs, so it’s worthwhile to ask if your policy includes this feature to protect your discounts after the first incident.
Understanding Coverage and Out-of-Pocket Expenses
Your insurance coverage type is crucial after a single-vehicle accident. Collision coverage usually handles repairs to your vehicle regardless of fault, while liability coverage typically won’t cover your damages. Comprehensive coverage may help if non-collision damage is involved, like weather-related issues. Also, keep in mind deductibles: a higher deductible means lower premiums but more out-of-pocket costs when filing a claim. Choosing a deductible you’re comfortable paying is essential.
Claims Process and Possible Policy Limitations
Filing a claim requires prompt reporting, accurate details, and supporting documentation like photos of the scene. Familiarize yourself with policy exclusions that could deny coverage, such as accidents involving driving under the influence, intentional damage, or unauthorized drivers. Proper documentation helps prevent delays or disputes during claims.
Long-Term Effects on Your Driving Record and Future Insurance
A single-vehicle collision typically stays on your driving record for several years, impacting your insurance risk and quotes if you shop around. Changing insurers post-accident may result in higher rates or fewer options, but good driving habits can improve rates over time. Annual policy comparisons are smart since discounts and pricing vary between companies.
Tips to Reduce the Insurance Impact
Stay proactive by maintaining safe driving habits, considering accident forgiveness options, bundling policies for discounts, and reviewing coverage regularly. These steps can help manage costs and keep your auto insurance affordable even after a single-vehicle incident.
Understanding how a single-vehicle collision affects your insurance helps you make informed decisions about your coverage, claims, and driving habits—protecting your finances and insurance future.
Newsletter Station provides professionally written, ready-to-send newsletters customized for your market and brand.
EXPLORE NEWSLETTER OPTIONS