
FEATURE ARTICLE
When to Insure Your Collectibles: Protecting What Matters Most
Apr 22, 2026
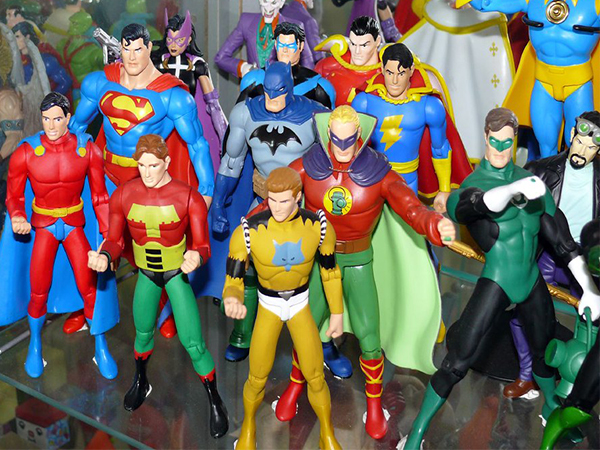
Collectibles often represent more than just monetary value—they reflect personal passion, history, and years of careful curation. From rare coins and vintage stamps to fine art and sports memorabilia, these items can appreciate significantly over time. As your collection grows, so does the need to protect it.
While many collectors assume their homeowners' insurance offers sufficient coverage, that’s not always the case. Specialized collectibles insurance can provide broader protection and peace of mind. Here’s how to determine when it’s time to insure your prized possessions—and how to do it wisely.
Key Signs It’s Time to Insure Your Collection
By recognizing the signs and taking proactive steps, you can safeguard your collection against unexpected loss while preserving its value for years to come. Whether you’re a seasoned collector or just getting started, the right coverage ensures your treasures remain protected every step of the way.
While many collectors assume their homeowners' insurance offers sufficient coverage, that’s not always the case. Specialized collectibles insurance can provide broader protection and peace of mind. Here’s how to determine when it’s time to insure your prized possessions—and how to do it wisely.
Key Signs It’s Time to Insure Your Collection
-
Your Collection Has Significant Monetary Value
As the financial value of your collection increases, so does your loss exposure. High-value items should be professionally appraised to establish accurate replacement costs. Updated appraisals also ensure your coverage reflects current market conditions. -
You Own Rare or Irreplaceable Items
Some collectibles are truly one-of-a-kind or extremely limited in availability. Whether due to historical significance or scarcity, these items can be impossible to replace. Insurance helps offset the financial loss and preserves the overall value of your collection. -
Your Items Are Vulnerable to Damage or Theft
Consider where and how your collectibles are stored. Are they exposed to risks such as:- Fire or water damage
- Theft or vandalism
- Environmental factors like humidity or sunlight
-
You Transport or Exhibit Your Collection
If you regularly move your collectibles—whether to shows, galleries, or storage—your risk increases. Transit and exhibition coverage can protect against accidental damage or loss outside your home, which standard policies often exclude. -
Your Homeowners Insurance Has Coverage Limits
Most standard homeowners' policies cap coverage for high-value items such as art, jewelry, or collectibles. These limits may fall well below your collection’s true value. A dedicated collectibles policy or rider (endorsement) can fill these gaps and provide more comprehensive protection. -
Market Values Are Changing
Collectible markets can fluctuate with trends, demand, and rarity. What was modestly valued a few years ago may now be worth significantly more. Regularly reviewing your policy ensures your coverage keeps pace with current valuations. -
You Want Greater Peace of Mind
Beyond the financial aspect, insurance provides reassurance. Knowing your collection is protected allows you to fully enjoy it—whether you’re displaying it, expanding it, or passing it down to future generations.
- Get professional appraisals every few years or after major acquisitions
- Document your collection with photos, receipts, and detailed descriptions
- Store items properly using climate control and secure storage solutions
- Work with a specialist insurer familiar with collectibles markets
- Review your policy annually to ensure accurate coverage
By recognizing the signs and taking proactive steps, you can safeguard your collection against unexpected loss while preserving its value for years to come. Whether you’re a seasoned collector or just getting started, the right coverage ensures your treasures remain protected every step of the way.