Know Your Coverage Inside and Out
When disaster strikes your home, property insurance is there to help ease the financial burden. But before filing a claim, take some time to understand your policy’s details. This includes what is covered—such as your dwelling, personal belongings, and additional living expenses—as well as your policy limits, deductibles, and any exclusions. Knowing these specifics upfront helps set clear expectations and guides your decisions throughout the claims process.
Act Promptly and Protect Your Property
Speed matters in a claims situation. Notify your insurance company right away to meet any reporting deadlines that could affect your coverage. If the damage poses a safety risk or could worsen—like a leaking roof or broken window—take reasonable steps to prevent further harm, such as placing a tarp or boarding up openings. However, hold off on permanent repairs until your insurance adjuster has conducted their inspection.
Document Everything Carefully
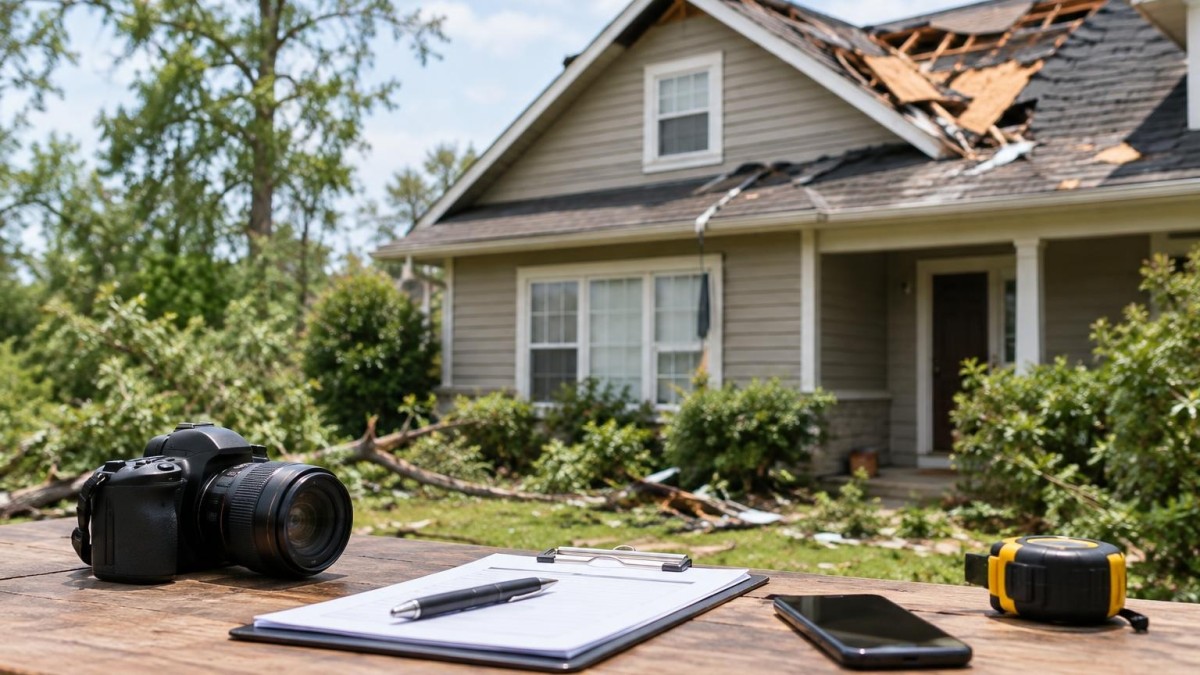
Solid documentation is the backbone of a smooth claim. Capture detailed photos and videos of all damage from multiple angles before starting repairs. Make an inventory of damaged or lost personal items, noting descriptions, purchase dates, and estimated values. Keeping these records organized can speed things up and clear up potential misunderstandings with your insurer.
Understand the Role of the Insurance Adjuster
After you report your claim, your insurer will usually assign an adjuster to assess the damage. Be thorough and honest when showing them all affected areas, including less obvious or structural issues. Ask questions about what they’re looking for, timelines, and what information you’ll need to provide. Good communication here helps ensure a fair evaluation and smoother proceedings.
Getting Repair Estimates and Handling Payments
Once the adjuster’s assessment is complete, you’ll likely need estimates from contractors. Choose licensed and trustworthy professionals who can provide detailed quotes outlining the work involved. While some insurers have preferred vendors, you’re generally free to select your own. Payments may be made directly to your contractors or reimbursed after repairs, so keep all receipts for materials, labor, and any temporary housing you might need.
Review and Negotiate Your Settlement
When you receive a settlement offer, review it carefully against your documented losses and your policy. If the offer doesn’t fully cover your damage, don’t hesitate to ask for clarification, negotiate, or provide additional evidence. You have the right to seek a settlement that truly reflects your losses.
Appealing Denials or Low Offers
If your claim is denied or the compensation is too low, you can usually appeal. Follow your insurer’s appeal process and submit any further documentation, specialist reports, or contractor evaluations that support your case. Staying organized and being persistent can make a big difference. Professional help from a public adjuster or attorney might also be worth considering if the dispute continues.
Navigating a property insurance claim can seem challenging, but being informed, responsive, and methodical can ease the process and help you secure the coverage and support you deserve to restore your home and peace of mind.
Newsletter Station provides professionally written, ready-to-send newsletters customized for your market and brand.
EXPLORE NEWSLETTER OPTIONS