Buying a home involves plenty of numbers—the purchase price, down payment, closing costs, monthly payment, property taxes, and insurance. One number that deserves attention well before you start making offers is your credit score.
Your credit can influence whether you qualify for a particular mortgage, the interest rate and fees you're offered, and ultimately how much it costs to finance your home. But there's an important distinction: your credit score isn't the only number a mortgage lender considers, and there isn't one universal score you must reach before you can buy a house.
Understanding how credit works before applying for a mortgage can help you avoid surprises and put yourself in a stronger position when you're ready to buy.
Understanding Credit Scores
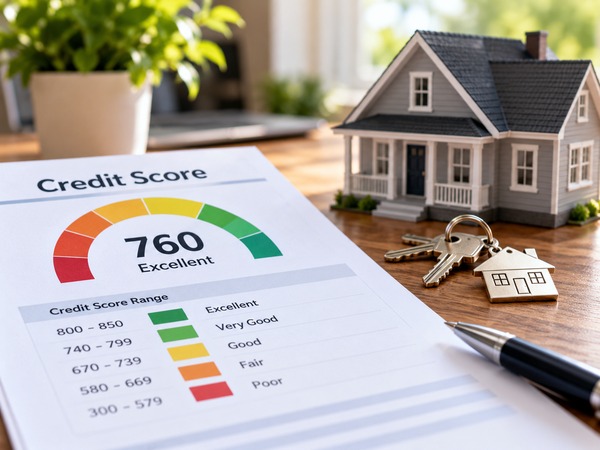
A credit score is a numerical representation of information in your credit report that helps lenders evaluate credit risk. Common credit scoring models use a range of 300 to 850, with higher scores generally indicating lower credit risk.
You also don't have just one credit score. Scores can differ depending on the credit bureau supplying the information, the scoring model being used, and when the score is calculated. The score you see through a bank, credit card company, or consumer credit-monitoring service may therefore be different from the score a mortgage lender obtains.
That's why prospective homebuyers should pay attention to both their credit scores and the underlying information on their credit reports.
How Your Credit Score Can Affect Your Mortgage Rate
One of the most important ways credit can affect a home purchase is through mortgage pricing.
Generally, borrowers with stronger credit profiles may qualify for more favorable mortgage rates and terms because lenders view them as presenting less credit risk. A lower score doesn't automatically prevent you from obtaining a mortgage, but it can result in a higher interest rate or additional loan-level pricing adjustments, depending on the loan and lender.
Even a relatively small difference in interest rate can matter when you're financing a home for 15, 20, or 30 years.
For example, rather than focusing only on the maximum purchase price a lender says you can afford, compare the estimated monthly payment and total borrowing costs at the rates you're actually being offered. The interest rate affects both.
And don't rely on old examples showing mortgage rates of 3% or 4%. Mortgage rates change with market conditions, so a realistic comparison should use current quotes for your loan amount, down payment, property type, and credit profile.
Is There a Minimum Credit Score to Buy a House?
There's no single minimum credit score that applies to every mortgage.
Requirements depend on the loan program, underwriting method, lender, and other aspects of the borrower's financial profile.
Conventional mortgage requirements have also changed. Beginning in November 2025, Fannie Mae's Desktop Underwriter, or DU, stopped requiring a minimum third-party credit score for DU loan casefiles. Instead, the automated system evaluates multiple aspects of a borrower's credit risk. Credit scores are still requested and can continue to affect mortgage pricing.
Manually underwritten loans can have different requirements, and individual lenders may apply their own standards.
Government-backed programs operate under separate rules. FHA financing, for example, has historically allowed some borrowers with lower credit scores to qualify, subject to FHA requirements and lender standards.
The practical takeaway is simple: don't assume you're automatically unable to buy a home because your score falls below a number you found online. Talk with a qualified mortgage professional about the programs and requirements that apply to your circumstances.
Your Credit Score Isn't the Whole Application
A strong credit score can help, but mortgage approval involves much more than the score itself.
Lenders may also evaluate your income, employment, existing monthly debts, available assets, down payment, credit history, property details, and debt-to-income ratio. Automated underwriting systems can consider multiple risk factors together rather than making a decision based solely on one three-digit number.
That explains why two homebuyers with similar credit scores don't necessarily receive identical mortgage offers.
It also means improving your overall financial position can matter alongside improving your score. Paying down debt, building cash reserves, and avoiding unnecessary new obligations before buying a home can strengthen other parts of your application.
How Credit Can Affect More Than Your Interest Rate
Credit can influence the cost and structure of a mortgage in several ways.
Depending on the loan program, your credit profile may affect the rate you're offered, pricing adjustments, mortgage insurance costs, or which financing options are available to you. Down payment, loan-to-value ratio, property type, occupancy, and other factors can interact with credit when determining loan pricing.
This is why it's worth comparing the complete Loan Estimate rather than choosing a mortgage based solely on the advertised interest rate.
Look at the rate, annual percentage rate (APR), estimated monthly payment, closing costs, lender credits, discount points, mortgage insurance, and cash required at closing. A low advertised rate isn't necessarily the least expensive option if obtaining it requires substantial upfront costs.
How to Prepare Your Credit Before Buying a Home
If you're planning to buy a home, reviewing your credit well before applying gives you time to address problems rather than discovering them while you're trying to close.
When Should You Check Your Credit Before Buying?
Earlier is better.
Checking your credit several months before you expect to apply for a mortgage gives you time to correct errors, reduce balances, establish a stronger payment history, and understand what a lender is likely to see.
You can review your credit reports online for free each week from Equifax, Experian, and TransUnion through AnnualCreditReport.com. Checking your own reports is considered a soft inquiry and doesn't hurt your credit score.
Remember that a credit report and a credit score aren't the same thing. Your reports contain the underlying account and payment information used by scoring models, while your scores are calculated from that information.
Avoid Major Financial Changes Before Closing
Getting preapproved isn't the end of the credit conversation.
Lenders may verify financial information again before closing, so major changes between mortgage approval and closing can create complications. Taking out a car loan, opening new credit cards, substantially increasing card balances, or making other significant financial moves can alter the information used to qualify you.
If you're under contract for a home and considering a major purchase or new loan, contact your lender before completing the transaction. Something that seems unrelated to your home purchase could affect your mortgage qualification.
Focus on Your Complete Financial Picture
A higher credit score can improve your mortgage options, but homebuyers shouldn't treat a particular score as the only goal.
Start by reviewing your credit reports, correcting genuine errors, paying bills on time, reducing unnecessary debt, and avoiding major credit changes as you approach your mortgage application. Then compare actual loan offers based on their complete costs—not simply the headline interest rate.
If your credit isn't where you'd like it to be, don't assume homeownership is automatically out of reach. Mortgage requirements vary, underwriting standards change, and lenders evaluate more than a credit score. Understanding your current financial position early gives you more time to determine what needs attention before you're ready to make an offer.
Newsletter Station provides professionally written, ready-to-send newsletters customized for your market and brand.
EXPLORE NEWSLETTER OPTIONS